.svg)


Former President Mohamed Nasheed and MDP President Abdulla Shahid have issued strong warnings to the government over depleted usable foreign reserves and uncoordinated economic policies threatening the tourism sector.
 News Desk
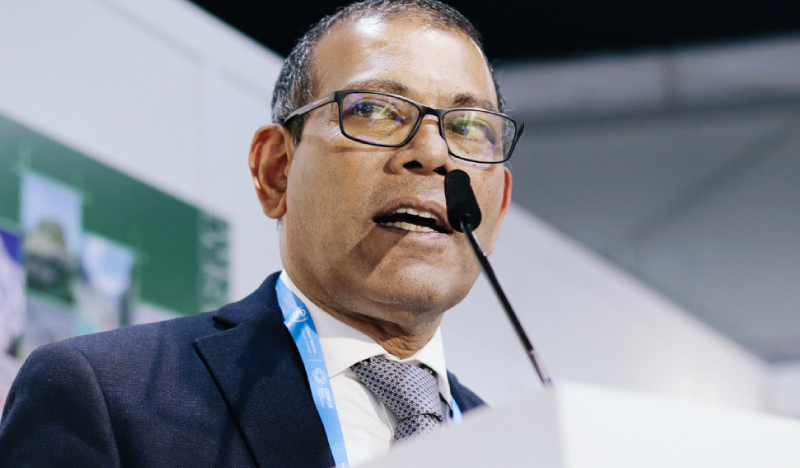
Former President Mohamed Nasheed - Photo: Climate Vulnerble Forum
MALÉ: Former President Mohamed Nasheed has warned that the state foreign exchange reserve is completely depleted, alleging that the government used public funds deposited at the Bank of Maldives to settle a 50 million dollar treasury bill.
In a social media post on X, Nasheed stated that dollar deposits made by businesses and citizens at BML are failing to reach foreign suppliers.
“There are no dollars in the state reserve at all. The $50 million T-Bill was paid using public funds at BML,” Nasheed wrote. “When businesses and citizens deposit dollars into BML to buy items, those dollars are not reaching the supplier because the government is taking those funds.”
Echoing those concerns, MDP President Abdulla Shahid warned that abrupt economic policies introduced without industry consultation are pushing the tourism sector toward a severe crisis.
“Due to the inconsistent and reckless changes being brought to policies by the government, the tourism industry today stands on the brink of falling into a deep abyss,” Shahid stated.
He urged authorities to hold immediate discussions with resort operators, adding, “I once again call on the government to abandon its stubborness, sit down for dialogue with tourism industry partners, listen to their voice, and start work immediately to save Maldivian tourism.”
Both opposition leaders cautioned that implementing top-down fiscal changes without broad consensus risks eroding investor trust and causing long-term damage to the national economy.
The disputed 50 million dollar payment is the third and final installment of a 150 million dollar debt facility subscribed by the State Bank of India in 2019 to assist with budget financing. While previous administrations requested annual rollovers, current administration officials confirmed that the full 150 million dollar facility has now been liquidated following three separate 50 million dollar installments cleared in January 2024, May 2026, and recently yesterday.